

Cherry: The Smarter Way to Pay
by Cherry Technologies, Inc.
4.5
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.5
- Price
- Free
- Download
- 100.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
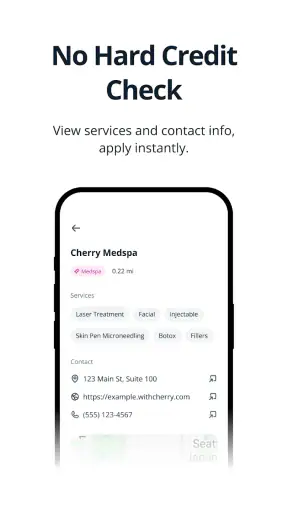
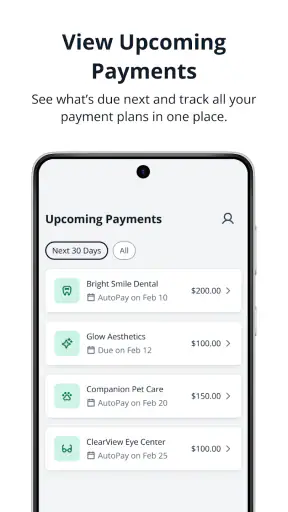
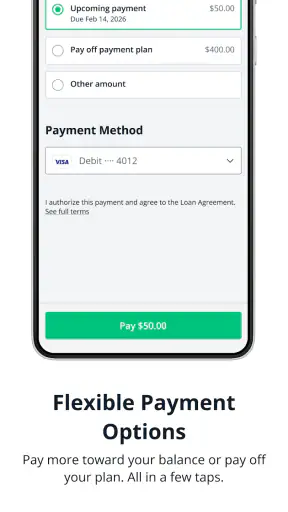
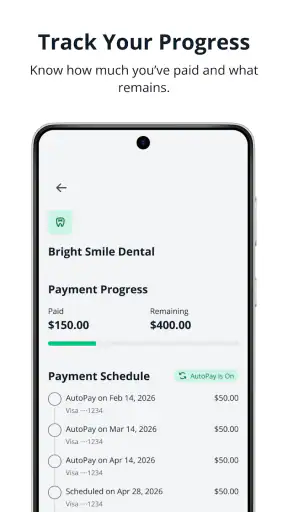
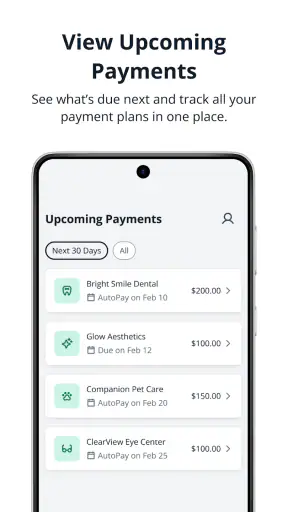
 Analysis by Getfullapps
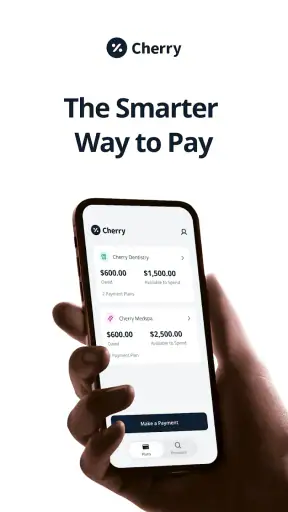
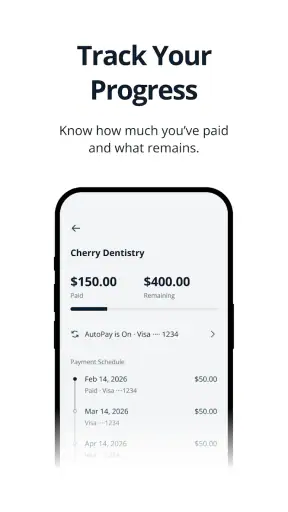
Paying for a planned expense can be awkward when the timing of your income and the timing of the bill do not line up. Cherry: The Smarter Way to Pay is built around that problem, presenting itself as a finance app for managing plans and paying on a schedule that suits you. I approached it less like a general budgeting tool and more like a focused payment companion: useful when you already know what you want to pay for, but need a clearer way to organize the timing.
That distinction matters. I would not treat Cherry as a replacement for a full banking app, a detailed household budget, or a conventional credit product without first checking whether its approach matches my needs. Its appeal is the plan-based experience. Instead of making every payment decision from scratch, I can think in terms of an upcoming commitment, the schedule attached to it, and whether that arrangement fits my cash flow.
The key question is simple: do you need more structure around planned payments, or do you need a complete view of your finances? If it is the first, Cherry deserves a closer look. If it is the second, a broader money-management app may be a better starting point.
How I judged Cherry as a payment-planning app
I judge Cherry by whether it helps me make a planned payment easier to understand, not by whether it can replace every part of my money routine. In this section, I look at the habits and practical checks that make a focused payment-planning app useful after the first few days. That distinction sets up a closer comparison with budgeting apps, manual reminders, and paying upfront.
The right problem to solve
When I assess an app in the finance category, I first ask what job it performs better than the usual alternatives. Cherry’s job is not presented as tracking every purchase, categorizing an entire bank account, or replacing all financial tools. Its focus is managing plans and paying according to a schedule. That makes the app most relevant to people who prefer to separate a planned expense from the rest of their day-to-day spending.
In practical terms, I would consider Cherry when an expense is important enough to plan but not convenient to pay all at once. A scheduled payment can be easier to handle psychologically and practically than an unplanned withdrawal. The benefit is not simply having another screen showing a balance. It is having a defined commitment that I can review before deciding whether it still fits my month.
This also creates the first trade-off. A plan can make a payment feel manageable, but it does not make the underlying expense disappear. I would use the app as a way to organize a commitment, not as permission to accept every payment arrangement offered to me.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
What I would check before committing
Before moving an existing payment routine into Cherry, I would look at four things: how clearly the plan is displayed, how easy it is to understand the schedule, how much control I have when circumstances change, and how quickly I can find the information I need. Finance apps earn trust through clarity. If I have to interpret vague labels or hunt through several screens to understand an upcoming payment, the convenience disappears.
I would also decide whether I want a dedicated payment-planning tool at all. Someone who already keeps a reliable spreadsheet or uses a banking app with strong scheduled-payment controls may not gain enough from adding another service. On the other hand, a person who repeatedly forgets when planned payments are due may value the separation and focus Cherry provides.
The app is free, which lowers the barrier to trying it. That does not remove the need to read each plan carefully before accepting it. Free access is useful for testing the workflow, but the real decision should be based on whether the schedule is understandable and practical for my own income pattern.
Who is likely to benefit most
I see the strongest fit for people who make planned purchases, prefer predictable payment timing, and want those commitments presented in one focused place. It may also suit users who feel overwhelmed by broad budgeting dashboards. A large financial overview can be valuable, but it can also bury the one upcoming payment I actually need to think about today.
Cherry may be especially approachable for someone who does not want to build a complicated budget before taking action. The plan-first idea gives the user a narrower task: understand the commitment, consider the timing, and keep an eye on what is coming next. That simplicity can be an advantage for people who abandon financial tools because they require too much setup.
I would be more cautious if my needs involve detailed investment tracking, business accounting, shared household finances, or a complete record of spending across multiple accounts. Those needs call for tools designed around reporting and aggregation rather than a focused payment schedule.
A realistic everyday situation
Imagine I have a larger planned expense arriving during a month when several ordinary bills are already due. Instead of treating the purchase as an isolated checkout decision, I can use Cherry to think about it as a plan. I would review the payment timing alongside my expected income, then decide whether the arrangement leaves enough room for essentials and unexpected costs.
The useful habit here is to check the plan before the payment date, not only after a problem appears. I would make that review part of my weekly money routine, alongside checking my account and upcoming bills. If the schedule no longer feels comfortable, that is the moment to investigate my options rather than waiting until the payment is imminent.
A less obvious benefit is that this approach can improve conversations about money. If I share expenses with a partner or family member, describing a purchase as a defined schedule may be clearer than saying only that it is “affordable.” The plan gives us something concrete to discuss: the commitment, the timing, and its place among other obligations.
The details that deserve extra attention
My first practical tip would be to distinguish the purchase decision from the payment decision. Cherry can help organize how a payment is made, but I would still ask whether the purchase itself is necessary, whether the timing is sensible, and whether the total commitment fits my wider situation. Separating those questions reduces the chance that a convenient schedule makes an unnecessary expense seem harmless.
My second tip would be to review plans whenever my income changes. A schedule that works during a strong month may feel very different after reduced hours, an unexpected repair, or another major bill. I would not assume that a previously comfortable plan remains comfortable automatically.
My third tip would be to use the app as a reminder for review, not as a substitute for reviewing my bank balance. A plan-centered view can be easier to understand than a full transaction history, but it may not show every other obligation affecting my available money. I would keep both perspectives in mind before making a new commitment.
Where Cherry stands out, and where another option may fit better
I see Cherry’s strongest case in giving planned payments a dedicated place, while its narrower focus is also the reason some people may be better served elsewhere. Here, I weigh the convenience against the attention a schedule still requires, and consider which alternative fits different routines. The next section turns that judgment into a practical recommendation about who is likely to keep using it.
Its advantage over ordinary budgeting apps
Traditional budgeting apps usually begin with income, spending categories, account balances, and targets. That is useful when I want a complete financial picture. Cherry takes a narrower route, which can be more comfortable when the immediate problem is a planned payment rather than uncontrolled spending.
The narrower scope may also reduce decision fatigue. Instead of asking me to classify every coffee, subscription, or grocery purchase, the app encourages attention on plans. For a user who has tried broad budgeting systems and stopped using them, that focused experience could be the difference between a tool that is opened occasionally and one that becomes part of a routine.
The trade-off is visibility. A general budgeting app may be better at showing how a payment affects the rest of my spending. Cherry’s focused approach is useful only if I remember to connect the plan with the wider financial picture myself. I would choose Cherry for payment organization, not for a full financial audit.
Its advantage over paying everything immediately
Paying in full is straightforward and avoids the need to manage a future schedule. For people with enough available cash and a preference for simplicity, that remains the cleaner option. There is no plan to monitor and no future commitment created by the purchase.
Cherry becomes more interesting when paying immediately would put unnecessary pressure on cash flow, while a structured schedule would remain realistic. The important word is realistic. I would compare the planned payments with essential costs first, then decide whether the flexibility is worth the added obligation.
This is where I would resist treating the app as automatically smarter than paying upfront. A schedule is not inherently cheaper, safer, or better. Its value depends on the user’s ability to follow it and understand the commitment. If I prefer to avoid future obligations entirely, the usual immediate-payment route may suit me better.
Its advantage over manual reminders and spreadsheets
A spreadsheet can be surprisingly effective for planned expenses. I can record the amount, date, and notes, then update it whenever something changes. Manual reminders are also familiar and flexible. For a highly organized person, those tools may be enough.
Cherry’s appeal is convenience and concentration. A purpose-built finance app can make the payment plan feel more like an active financial task than a row in a document I may forget to open. That matters for users who understand what they should do but struggle to maintain a manual system.
Still, switching from a spreadsheet is not automatically worthwhile. I would compare the time required to recreate my existing plans with the practical improvement I expect afterward. If my spreadsheet already gives me a clear view and I rarely miss a review, staying with it may be the more efficient choice.
When a broader financial service is the better answer
I would look beyond Cherry if I needed account aggregation, detailed spending analysis, long-term financial goals, or extensive reporting. Those functions belong naturally to broader personal-finance platforms. I would also prefer a more comprehensive tool if several people needed to manage the same household picture and the app’s plan-focused workflow did not cover that comfortably.
Likewise, users who want investment information, tax organization, debt analysis, or business records should not select Cherry simply because it is free and easy to try. The right category matters more than the convenience of downloading another app. Cherry is most compelling when the central need is payment planning, not financial administration in general.
What switching would actually involve
Moving to Cherry would not only mean installing an app. I would need to identify the plans I currently manage elsewhere, check their dates and amounts, and decide which ones belong in the new workflow. That small preparation step is important because incomplete information can make any finance app look unreliable.
I would start with one planned expense rather than transferring everything at once. That gives me a low-risk way to learn how the app presents the schedule, how quickly I can locate the next payment, and whether the routine feels natural. After a few reviews, I could decide whether Cherry deserves a larger role in my finances.
Keeping the old method available during the transition is sensible. I would not delete reminders or discard records until I had confirmed that the new routine works for me. This is one of the less obvious costs of switching: the app may be free, but my time and attention are still resources.
Version, accessibility, and audience
Cherry is developed by Cherry Technologies, Inc. and is currently at version 1.3.0. It is free to use, carries an Everyone content rating, and supports devices running Android 7.0 or later. Those details make it accessible to a wide range of Android users, including people who are not using the newest phone.
The app’s average rating is 4.5 from around one hundred ratings, with about fifty written reviews, and it has passed one hundred thousand installs. I read those figures as a sign of meaningful early interest rather than as proof that the app will suit every financial routine. A finance app can receive positive feedback for being simple while still being the wrong choice for someone who needs advanced account management.
The February 20, 2026 release date also places Cherry in a relatively new stage of its life. That can be encouraging because the product may feel focused and actively shaped, but it also makes me more careful about relying on it as my only record for important commitments. I would keep essential payment information accessible elsewhere until the workflow had earned my confidence.
My recommendation after weighing the trade-offs
I recommend Cherry to someone who wants a straightforward way to organize planned payments and who finds full budgeting systems too broad or demanding. I would particularly suggest trying it if payment timing is the part of personal finance that causes the most stress. The free price makes a cautious trial reasonable, and the focused concept is easier to evaluate than a tool that attempts to manage everything.
I would not recommend it as the only finance app for someone who needs a complete household dashboard, detailed spending categories, investment oversight, or business-level records. I would also skip it if I already have a reliable payment calendar and no difficulty maintaining it. In that situation, switching creates work without solving a real problem.
My preferred way to begin is deliberately small: choose one upcoming plan, inspect its schedule, compare it with essential expenses, and revisit the arrangement before the payment is due. If Cherry makes that process clearer without encouraging me to overextend, it has earned a place in my routine. If it merely adds another screen while my existing method already works, I would stay with the simpler option.
Overall, I see Cherry: The Smarter Way to Pay as a focused planning tool rather than a universal money manager. Its strongest quality is the decision framework it encourages: identify the commitment, understand the timing, and judge it against real cash flow. That is valuable, provided I remain honest about what the app can organize and what still requires my own financial judgment.
Pros
- Simple interface makes everyday payments easy to manage.
- Clear spending overview helps users track purchases in one place.
- Useful payment reminders can help reduce missed due dates.
- Quick access to transaction details improves payment organization.
- Convenient mobile access eliminates the need for paper statements.
Cons
- Availability and features may vary depending on your country.
- Some services may require identity verification before use.
- Payment options can be limited by supported merchants or providers.
- App performance may depend on your bank or payment network.
- Customer support response times may vary during busy periods.
FAQs for Cherry: The Smarter Way to Pay
What is Cherry: The Smarter Way to Pay?
Cherry is a healthcare financing and payment platform that allows eligible patients to split the cost of treatments into manageable installments. It is commonly offered by participating medical, dental, cosmetic, and wellness providers at checkout. Instead of paying the entire amount upfront, users can apply for a payment plan, review the available terms, and complete the purchase through Cherry if approved.
How does applying for a Cherry payment plan work?
The application process is generally completed through a participating provider or the Cherry app and may require basic personal, contact, and financial information. Cherry typically performs an eligibility or credit assessment before showing available options. Approval is not guaranteed, and the payment amount, term, interest, and other conditions can vary depending on the applicant, purchase, and plan offered.
Does Cherry charge interest or additional fees?
Cherry payment plans can have different pricing structures, so users should carefully review the offer before accepting it. Some plans may advertise promotional or low-interest terms, while others may include interest, administrative costs, late fees, or other charges. The exact annual percentage rate, total repayment amount, due dates, and applicable fees should be confirmed in the agreement rather than assumed from promotional wording.
Can I use Cherry for any purchase or healthcare provider?
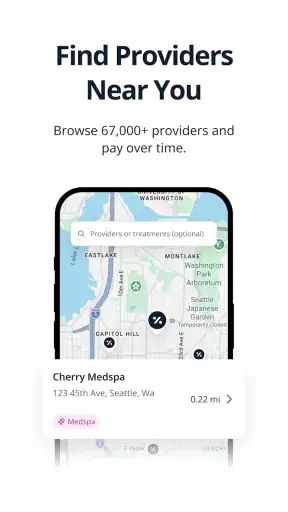
Cherry is not a general-purpose payment service that works at every store or with every professional. Its availability depends on whether the healthcare or wellness provider participates in the Cherry network and whether the specific treatment qualifies. Before downloading or applying, check with the provider to confirm that Cherry is accepted, which services are eligible, and whether the desired payment plan is available for your purchase.
What should I know about repayments, cancellations, and support?
After accepting a plan, users are responsible for making scheduled payments according to the agreement, even if they stop using the app. It is important to keep payment details current and contact Cherry or the provider promptly about refunds, cancellations, treatment changes, or billing concerns. The provider may handle service-related issues, while Cherry generally handles financing and account questions, so keeping both parties informed is recommended.

Cherry: The Smarter Way to Pay
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@withcherry.com, visit https://withcherry.com, or review their https://withcherry.com/privacy.










